: P2S: Send Money Easily – Features and Complete Guide
Introduction to P2S
Digital payments have changed the way people manage money and complete everyday financial activities. Instead of depending entirely on cash or visiting a physical payment location, people increasingly use digital platforms to send money, receive payments, and manage their financial information. P2S, presented with the slogan “Send Money Easily,” represents this type of digital payment experience.
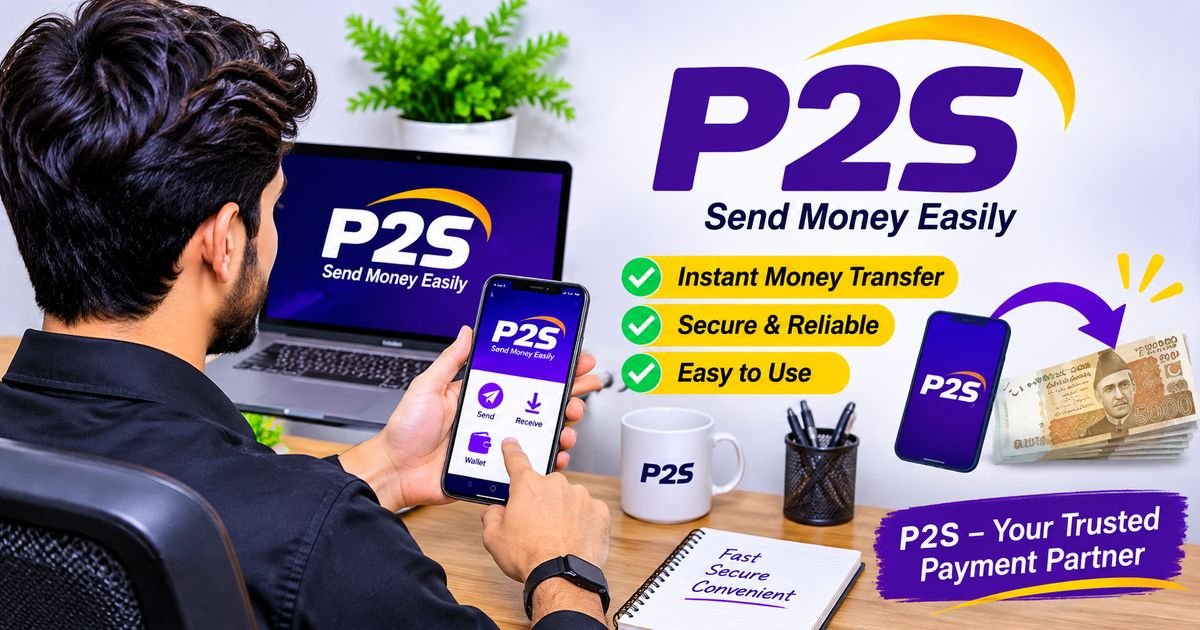
The P2S branding focuses on making money transfers straightforward through a mobile-friendly interface. Its promotional design highlights several important functions, including sending money, receiving payments, and accessing a digital wallet. It also emphasizes convenience, fast transfers, and a simple user experience.
Digital payment platforms are useful because they can reduce the number of steps involved in ordinary transactions. For example, someone who needs to transfer money to another person may prefer a mobile payment option instead of arranging a cash exchange. Similarly, a small business may find digital payment methods convenient for managing customer transactions.
P2S is presented around these everyday payment needs. Its visual identity uses a purple-and-yellow design, with the main message focusing on accessible money transfers.
However, it is important to distinguish between features shown in promotional material and independently verified service capabilities. The available P2S image highlights sending, receiving, and wallet functions, but does not establish its ownership, regulatory status, transaction limits, fees, or supported countries.
This guide explores P2S, its advertised functions, the role of digital wallets, payment convenience, security considerations, and the factors users should understand before choosing a digital money transfer service.
What Is P2S?
P2S is presented as a digital payment service focused on making money transfers easier. Its promotional identity emphasizes the idea of sending and receiving money through a convenient digital experience.
The displayed interface includes options labeled Send, Receive, and Wallet. These functions represent three common components of mobile payment platforms.
The Send option represents the process of initiating a payment to another recipient. The Receive option relates to accepting incoming payments. The Wallet section represents a digital area for managing payment-related information.
These functions are familiar to people who use modern financial applications.
Instead of treating every transaction as a separate activity, digital payment services can bring different payment operations together within one interface.
The main purpose of a platform with these functions is to make routine financial activities easier to understand and manage.
P2S also uses the message “Send Money Easily,” suggesting that simplicity is an important part of its intended identity.
Before using any service carrying the P2S name, users should identify its official provider and verify whether the application is available and authorized in their location.
Understanding the P2S Digital Payment Concept
The idea behind P2S is connected to the wider development of digital financial services.
Traditional money transfers can involve physical cash, banking visits, paperwork, or coordination between people.
Digital payment platforms offer another approach by providing electronic interfaces through which financial transactions can be requested and managed.
A typical digital payment experience involves several stages.
First, a user accesses an account through a supported application or platform. The user then selects an available payment function and provides the required information.
The system processes the request according to its supported payment methods and applicable conditions.
After processing, the platform may provide a transaction confirmation or status notification.
P2S’s advertised Send, Receive, and Wallet options reflect this general digital payment model.
The exact process, however, depends on the actual P2S service and its technical implementation.
Main Features Highlighted in P2S
The promotional image identifies several features that explain the service’s intended direction.
Send Money
The Send option is one of the main functions displayed in the P2S interface.
Money transfer functionality allows users to initiate payments to another person or an eligible destination.
In digital payment applications, this process commonly involves selecting a recipient and entering the relevant payment information.
Some services support transfers between registered users, while others may offer additional payment methods.
The available P2S promotional material identifies a sending function but does not specify which transfer networks or payment methods are supported.
For users, the most important consideration is whether the service supports their intended type of transaction.
A clear payment interface can also help reduce mistakes when entering recipient details.
Receive Money
Receiving payments is another function shown in the promotional image.
This feature represents the ability to accept incoming funds through a supported payment system.
Receiving money can be relevant for individuals, freelancers, service providers, and businesses.
For example, a person providing a digital service may prefer receiving an electronic payment instead of arranging a cash exchange.
A business may also use digital payment options to make customer transactions more convenient.
The actual receiving process depends on the service’s supported payment methods and account requirements.
Users should always check the transaction status inside the official application rather than relying only on screenshots or messages sent by another person.
Digital Wallet
The P2S promotional interface also includes a Wallet option.
A digital wallet is an electronic environment used to manage payment-related information and, depending on the provider, available funds.
Different wallet services offer different capabilities.
Some allow users to maintain a stored balance, while others connect directly to external financial accounts or payment methods.
A wallet may also provide access to transaction records, payment information, or account settings.
The exact capabilities of the P2S wallet are not established by the promotional image.
Users should review the official service documentation to understand whether it stores funds, connects to another account, or simply provides a payment management interface.
Instant Money Transfer
The P2S promotional design highlights Instant Money Transfer as an important message.
Fast payment processing is a valuable feature in digital financial services because users generally want to complete transactions without unnecessary delays.
However, the word “instant” can describe different things.
Some platforms process transfers immediately between supported accounts, while other payments may take additional time because of verification, banking schedules, payment networks, or security reviews.
For this reason, users should check the actual processing conditions before relying on a particular transfer time.
The availability of instant transfers should be confirmed through the official P2S provider.
Simple User Experience
The promotional material also highlights ease of use.
A simple interface can make digital financial services more accessible to people who do not have extensive experience with payment applications.
Clearly labeled options help users understand where to find important functions.
For example, separating Send, Receive, and Wallet activities can make the main interface easier to navigate.
Good application design should also provide understandable instructions, transaction summaries, and clear notifications.
A user should be able to identify the amount, recipient, and payment status without unnecessary confusion.
How Digital Money Transfers Work
Understanding the general payment process can help users make better decisions when selecting a digital financial service.
A digital money transfer normally involves communication between the sending platform, the payment provider, and the receiving destination.
The sender begins by selecting an available payment method.
The application then collects the information required to identify the recipient and the intended amount.
Depending on the service, the system may perform identity checks, account validation, balance verification, or additional security reviews.
After the necessary checks, the payment request is submitted for processing.
The receiving side may then display the incoming payment or provide a confirmation when the transaction has been completed.
Some services process transactions internally, while others depend on external banking or payment networks.
These differences explain why transaction times and availability can vary between providers.
The specific technical arrangement used by P2S is not established by the available promotional information.
Why Digital Wallets Are Becoming Popular
Digital wallets have become an important part of modern financial technology.
Their popularity is connected to convenience, smartphone adoption, and the increasing availability of electronic payment services.
Convenient Access
A digital wallet can provide access to payment-related functions through a mobile interface.
This can reduce the need to carry certain payment details separately.
Users may be able to review available information and manage supported transactions through one application.
Better Organization
Some wallet platforms provide transaction histories and account summaries.
These records can help users understand their payment activity.
Keeping electronic records can also make it easier to review previous transactions when resolving a payment question.
Reduced Dependence on Physical Cash
Digital payment options provide an alternative to cash for supported transactions.
This can be useful for online purchases, service payments, and transfers between eligible accounts.
However, cash may still be necessary in locations where digital payment acceptance is limited.
Easier Payment Management
When different payment functions are available in one place, users may find routine financial activities easier to organize.
The value of this arrangement depends on the features offered by the actual provider.
P2S and Everyday Financial Activities
The P2S promotional concept focuses on common payment activities rather than a single specialized financial task.
This makes it relevant to several possible situations.
Personal Money Transfers
People frequently need to exchange money with family members, friends, or other individuals.
Digital payment services can provide an alternative to physical cash exchanges when both parties have access to a supported payment method.
The sender and recipient should always verify the transaction details before confirming a transfer.
Freelance Payments
Freelancers often work with clients who need convenient ways to pay for completed services.
A digital payment platform may be useful when it supports the relevant payment arrangement.
However, freelancers should check supported currencies, withdrawal options, fees, and payment restrictions before choosing a provider.
Small Business Transactions
Small businesses may benefit from payment services that make receiving money more convenient.
A digital payment option can support customer transactions and reduce dependence on manual cash handling.
Business owners should also understand transaction records, settlement times, and applicable financial requirements.
Online Services
Digital platforms can be useful when payments are made remotely.
For example, an online service provider may need to collect payments from customers without meeting them physically.
The availability of this option depends on the payment service’s supported regions and transaction methods.
P2S User Interface and Visual Design
The promotional image uses a distinctive purple-and-yellow visual identity.
Purple is used prominently for the P2S branding, while yellow highlights the main service messages.
Green check marks appear alongside three advertised benefits: Instant Money Transfer, Secure and Reliable, and Easy to Use.
The design also displays a mobile phone, laptop, and a separate smartphone illustration.
These visual elements communicate the idea of accessing a payment service through digital devices.
The Send, Receive, and Wallet labels are particularly important because they communicate the main functions without requiring a lengthy explanation.
Good financial application design should make important information easy to identify.
Users should be able to distinguish account information from payment actions and understand when a transaction requires confirmation.
The promotional design provides an overview of the intended user experience, but it does not establish the appearance or functionality of an actual downloadable application.
Security Considerations for Digital Payment Services
Security is an essential consideration whenever money is managed electronically.
A payment platform should use appropriate safeguards to protect account information and financial transactions.
The P2S promotional image includes the phrase Secure and Reliable.
However, this is an advertising statement rather than independent evidence of a particular security certification or regulatory approval.
Users should investigate the actual provider before trusting a service with financial information.
Account Protection
Payment services should provide appropriate account protection.
Depending on the platform, this may include passwords, additional authentication, account verification, and device security controls.
Users should avoid sharing login credentials with other people.
Transaction Verification
Payment information should be reviewed before a transaction is confirmed.
The recipient’s details and payment amount should match the intended transaction.
This is especially important because transferring money to an incorrect recipient may be difficult to reverse.
Privacy Protection
Financial applications may process personal information as part of account creation and transaction management.
Users should understand what information is collected and how it is used.
A clear privacy policy should explain the provider’s data practices.
Fraud Awareness
Unexpected payment requests should always be treated carefully.
Users should avoid trusting messages that promise guaranteed rewards or demand urgent transfers.
They should also verify that they are using the provider’s genuine website or application.
Device Security
The security of a payment account also depends on the device used to access it.
Keeping a smartphone updated and using a secure screen lock can help protect personal information.
Users should avoid accessing financial accounts through unfamiliar or untrusted applications.
What to Check Before Using P2S
Before using P2S for an actual financial transaction, it is important to identify the official service and verify its details.
The promotional image alone is not enough to establish whether a financial provider is legitimate or suitable for a particular user.
Official Website or Application
Look for the official P2S website or verified application listing.
Check the developer or company name and make sure it matches the service you intend to use.
Avoid downloading financial applications from unknown sources.
Company Information
Find out which company operates the service.
Reliable financial providers should make important business information available to users.
Regulatory Status
Check whether the provider is authorized to offer the relevant financial services in the country where you intend to use it.
Requirements differ between countries and types of payment services.
Transaction Fees
Some digital payment platforms charge fees for particular transactions.
These may depend on the payment method, destination, currency, or transaction amount.
Review the complete fee information before making a payment.
Transfer Limits
Payment services may impose minimum and maximum transaction amounts.
They may also apply daily, monthly, or account-specific limits.
The relevant limits should be confirmed through official documentation.
Withdrawal Options
If a service includes a wallet balance, users should understand how funds can be withdrawn.
Check supported withdrawal methods, processing times, and associated charges.
Customer Support
A reliable financial service should provide a clear way to contact its support team.
This becomes especially important when a payment is delayed, an account is restricted, or a transaction needs investigation.
P2S for Individuals
Individuals may be interested in digital payment services because they want a convenient way to manage ordinary financial activities.
A service offering sending, receiving, and wallet functions can potentially bring these tasks together.
For example, someone may need to receive a payment from another person and later use an available balance for a supported transaction.
Having clearly separated payment options can make the process easier to understand.
However, users should not assume that every digital wallet supports every type of transfer.
The actual P2S service conditions determine which activities are available.
People should also consider their personal payment needs before creating accounts with additional financial providers.
P2S for Freelancers and Independent Workers
Independent workers frequently use digital payment methods to manage income from services.
Writers, designers, developers, consultants, and other freelancers may receive payments from different customers.
A suitable digital payment service can make it easier to organize incoming transactions.
The most important considerations include supported payment methods, currency availability, transaction costs, and withdrawal arrangements.
Freelancers should also maintain their own financial records.
An application transaction history can be useful, but it should not automatically replace proper bookkeeping.
Before relying on P2S for freelance income, users should confirm whether it supports the countries and payment arrangements involved.
P2S for Small Businesses
Small businesses often need convenient payment methods for customers.
A digital payment platform may help a business manage incoming transactions without relying entirely on physical cash.
However, business requirements can be different from personal payment needs.
A business may require transaction reports, account permissions, payment confirmations, settlement information, and customer support.
It may also need to follow local tax and financial regulations.
Business owners should therefore review the actual capabilities of P2S rather than assuming that its promotional Send and Receive buttons represent a complete business payment system.
The right platform should support the business’s operational requirements and provide transparent information about costs and responsibilities.
Digital Payments and Financial Record Keeping
Keeping accurate financial records is important for both individuals and businesses.
Digital payment platforms may provide transaction histories that help users review their financial activity.
A record may contain information such as the transaction date, amount, payment status, and available reference details.
These records can help users investigate questions about previous payments.
For example, if a recipient does not recognize an incoming payment, a transaction reference may help the provider investigate the issue.
Users should understand how long records remain available and whether they can export statements.
It is also sensible to maintain independent records for important business transactions.
The available P2S promotional material does not confirm which reporting or export features its wallet provides.
Advantages of Digital Money Transfer Platforms
Digital money transfer services can provide several practical advantages when their features are reliable and suitable for the user’s needs.
Convenience
A mobile payment interface can make supported financial activities easier to access.
Users may be able to manage payments without visiting a physical location.
Faster Communication
Digital platforms can provide transaction updates through their applications or other supported notification methods.
This helps users understand whether a payment request has been received or processed.
Electronic Records
Transaction histories can provide useful information about previous financial activity.
This can make it easier to review payments and identify unusual entries.
Flexible Payment Options
Depending on the provider, users may have access to different ways of sending and receiving money.
However, the available methods should always be checked before creating an account.
Centralized Interface
A platform that brings payment and wallet functions together can make routine activities easier to organize.
These advantages depend on the actual service design, supported networks, and account conditions.
Possible Limitations of Digital Wallet Services
Digital payment applications also have limitations.
Understanding these issues helps users make more informed decisions.
Internet Availability
Many mobile payment services require an internet connection.
A weak connection can interrupt account access or delay transaction updates.
Service Availability
Some financial services are restricted to particular countries or regions.
A platform may not support every recipient or payment destination.
Transaction Charges
Certain payment operations may involve fees.
Users should review the charges before choosing a service.
Verification Requirements
Financial providers may request identity information before allowing particular account functions.
These requirements can vary according to the service and local regulations.
Technical Problems
Applications may experience maintenance periods, connection problems, or temporary service interruptions.
Users should understand the official support process for resolving payment issues.
Dependence on the Provider
Digital wallet services depend on the provider’s systems and operating conditions.
Users should understand what happens to their account and available funds if a service becomes unavailable.
How to Compare P2S With Other Digital Payment Services
Choosing a payment platform should involve more than comparing promotional slogans.
A useful comparison focuses on the actual services available to customers.
First, check whether each platform supports the required payment destination.
A service that offers domestic transfers may not necessarily support international payments.
Second, compare transaction costs.
A platform with a simple interface may still charge fees for certain payment activities.
Third, review security and account verification arrangements.
Financial services should explain how they protect user information and handle suspicious activity.
Fourth, examine withdrawal and settlement options.
These details matter when users need access to funds within a particular period.
Finally, compare customer support and complaint procedures.
A provider should explain how customers can report payment problems and request assistance.
Without verified information about P2S pricing, supported networks, and regulatory arrangements, it would not be accurate to claim that it is better than another named payment provider.
The Role of Mobile Applications in Modern Payments
Smartphones have become important tools for managing everyday digital activities.
People use mobile applications for communication, shopping, banking, entertainment, and financial organization.
Payment applications fit naturally into this environment because they allow supported financial activities to be accessed through a familiar device.
A well-designed application should make navigation straightforward.
Important information should be presented clearly, and users should understand when an action will initiate a financial transaction.
Mobile interfaces should also work across supported screen sizes and provide understandable notifications.
The P2S promotional design uses smartphone screens to communicate this mobile-first payment concept.
However, actual device compatibility and application availability should be confirmed through an official source.
Responsible Use of Digital Payment Services
Responsible payment habits are important regardless of which provider someone chooses.
Users should always check recipient information before confirming a transfer.
They should keep their account credentials private and avoid responding to suspicious payment requests.
It is also useful to review transaction records regularly.
Unexpected account activity should be reported through the provider’s official support channel.
For larger transactions, users should understand applicable limits and any verification requirements.
Financial applications are tools for managing payments, but users remain responsible for checking the details of the transactions they authorize.
Common Questions About P2S
What Is P2S?
P2S is presented in its promotional material as a digital money transfer service with Send, Receive, and Wallet functions.
What Does the P2S Slogan Mean?
The slogan “Send Money Easily” communicates the service’s focus on convenient digital money transfers.
Does P2S Support Sending Money?
The promotional image displays a Send option, indicating that sending money is one of its advertised functions. The exact supported transfer methods should be confirmed with the official provider.
Can Users Receive Money Through P2S?
The promotional material includes a Receive option. The actual receiving process and supported payment methods require confirmation from the service provider.
Does P2S Have a Digital Wallet?
A Wallet option is visible in the advertised interface. Its exact functionality, including whether it stores a balance or connects to external accounts, has not been established by the available information.
Is P2S an Instant Money Transfer Service?
The promotional image advertises Instant Money Transfer. Actual processing times may depend on the payment method, destination, verification requirements, and provider conditions.
Is P2S Safe to Use?
The promotional material describes P2S as secure and reliable, but this statement alone does not verify its security standards. Users should investigate the provider, privacy policy, regulatory status, and security arrangements before using it.
Does P2S Charge Transaction Fees?
The available promotional image does not provide fee information. Users should consult official pricing documentation before making transactions.
Is P2S Available in Pakistan?
The image does not establish which countries P2S supports. Users in Pakistan should verify the provider’s official availability and authorization before registering or transferring money.
Can P2S Be Used for Business Payments?
The advertised Send and Receive functions suggest a general payment use case. However, business account support, merchant services, and transaction reporting have not been confirmed.
Does P2S Require Account Verification?
The available information does not explain its registration or verification requirements. These should be checked through the official provider.
Where Can Users Find P2S Customer Support?
The promotional image does not show an official website, support address, telephone number, or contact page. Users should obtain support information directly from a verified official source.
Final Thoughts
P2S is presented as a digital payment concept focused on making money transfers easier through a mobile-friendly experience. Its promotional identity highlights three main functions: sending money, receiving payments, and accessing a digital wallet.
The design also emphasizes convenience, instant transfers, and secure payment experiences. These are important themes in modern financial technology because users increasingly expect payment services to be accessible and straightforward.
However, choosing a financial platform requires more than looking at its promotional features. Users should verify the official provider, supported countries, transaction charges, security arrangements, regulatory status, and withdrawal conditions before using any service.
Understanding these details can help individuals and businesses make better payment decisions.
Overall, P2S communicates a simple idea: bringing everyday money transfer activities into a convenient digital environment. Its actual usefulness will depend on the services, protections, and payment options confirmed by its official provider.